






Explore, compare, move forward
Mortgage insurance: compare before you choose
Enter your project to compare available proposals for your profile. Our team in Gex helps you understand prices and cover.
Free, with no obligation
 Personal advice, every step of the way.
Our clients’ reviews on Google Read reviews
Comparing mortgage insurance beyond the price
Mortgage insurance covers certain loan repayment risks, depending on the policy. Whether you are arranging a new loan or changing insurance, compare cover as well as premiums. Alperea helps you review proposals and your lender’s requirements.
Estimate your mortgage insurance
Enter your project to compare available proposals for your profile. Our team in Gex helps you understand prices and cover.
Start my simulationUnderstanding insurance delegation
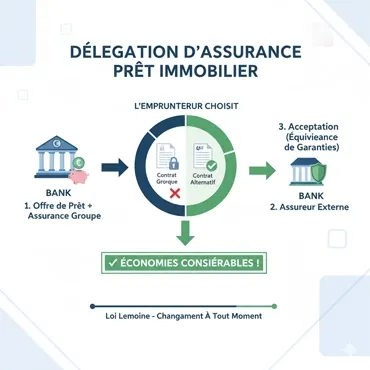
You can compare the policy offered by your bank with other insurers’ proposals. An external policy must meet the level of cover required by your lender. Our team helps you understand those requirements and the proposed terms.
Guarantees not to be overlooked
Review the cover required by the lender and the actual policy conditions:
- Death and total and irreversible loss of autonomy (PTIA): check the insured amount, exclusions and age limits in the policy.
- Incapacity and disability (ITT, IPT, IPP): check definitions, waiting periods and the occupation assessed, particularly if you work in Switzerland.
- Back and psychological conditions: check exclusions and any optional cover conditions rather than assuming these conditions are covered.
Group insurance vs. Delegation: The comparison
The choice isn't just about the price. Here are the main differences:
| Criterion | Bank insurance (group) | External insurance (delegation) |
|---|---|---|
| Pricing | The bank’s proposal sets out the premium and how it is calculated. | A proposal based on your profile and the insurer’s terms. |
| Cover | Review the proposed policy terms and the lender’s requirements. | Compare with the lender’s requirements and your cover needs. |
| Flexibility | Changing insurance is possible under the rules applicable to your loan. | The new policy must meet the equivalent cover required by your lender. |
To assess any difference in cost, compare policies for the same loan amount, duration and insured shares, without overlooking cover. Your adviser can help you understand the differences between proposals.
Frequently asked questions about mortgage protection
? Can I change insurance during my mortgage?
For loans and policies covered by the French rules, the Lemoine law allows a change at any time, subject to equivalent cover accepted by the lender. CHF alone does not determine which law applies. Coordinate lender approval, cancellation and the new policy’s start date to maintain continuous cover.
? Can my bank refuse an external policy?
Under the relevant French rules, the lender cannot refuse a policy with an equivalent level of cover. It must respond within ten working days and give all reasons for any refusal. Substitution cannot justify changing the loan rate or terms, or charging additional bank fees. Any fees for the new policy or intermediary must be identified separately.
? How should each borrower’s insured share be chosen?
The insured share is the proportion covered for each borrower. The lender’s requirements specify the expected level, often at least 100% of the loan in total. The allocation depends on the case and cover: this is not a universal legal minimum. Compare proposals using the same insured shares.
How do you choose mortgage protection insurance?
Mortgage protection insurance and the Lemoine Act: read the full guide

